How My Family Earns 5% Cash Back at Costco (And Effectively Doubles Our Rewards Cap)
The "Toddler Tax" and Our Costco Addiction
If you have a toddler, you know that your house eats berries, diapers, and organic pouches at an alarming rate. Since our little one started eating solids, our Costco runs have shifted from "occasional stock-up" to "weekly survival ritual."
By my back-of-the-envelope calculations, our household is now firmly in the top 2% of Costco spending households. We aren’t just buying bulk; we are living in bulk. But as a finance nerd (and the builder of the CardSavvy Optimizer), I couldn’t just watch those receipts print out without optimizing every dollar.
Here is the exact math behind how my spouse and I stack memberships and credit card multipliers to get a 5% return on our Costco spending, and how we structured our accounts to bypass the annoying quarterly caps.
Layer 1: The Executive Membership Math
First, the basics. We upgraded to the Costco Executive Membership.
- Cost: $130 annual fee ($65 more than the standard Gold Star membership).
- Benefit: 2% annual reward on qualified Costco purchases (capped at $1,250/year).
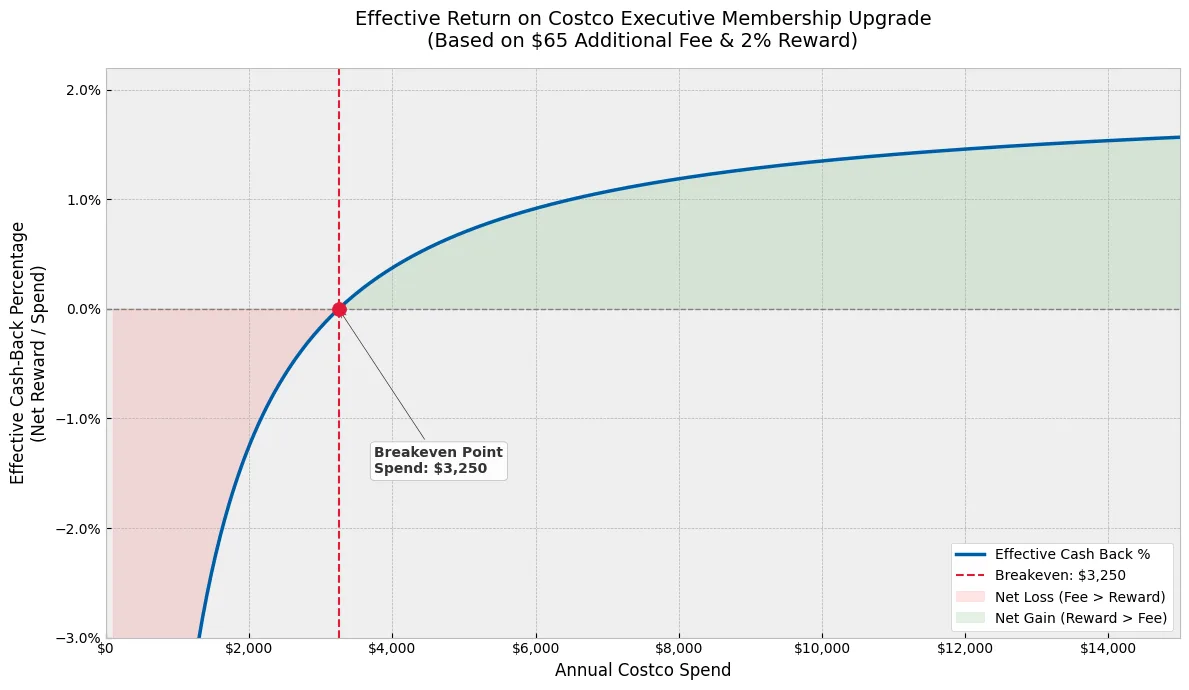
The Break-Even Point: To recoup the extra $65 upgrade fee, you only need to spend $3,250 a year (about $271/month) at Costco. Since we blow past that number every year, this was a no-brainer. This earns us our first 2% back.
Layer 2: The Bank of America Relationship Multiplier
This is the second layer. Rather than the Costco Citi card, which earns 2% at Costco, we pay with the Bank of America® Customized Cash Rewards credit card.
Standard users get 2% cash back at wholesale clubs. We hold over $100,000 in assets in a linked Merrill Edge brokerage account, which puts us at the Preferred Honors tier of BofA Rewards.
The Multiplier Effect: Preferred Honors members receive a 50% rewards bonus on their credit cards.
- Base Reward: 2% on Wholesale Clubs
- Multiplier: 1.5x (2% base + 50% bonus)
- Total Cash Back: 3.0%
This post used to say 3.5%, for a 5.5% stack. Bank of America retired Preferred Rewards on May 27, 2026 and replaced it with BofA Rewards. Under the old program $100,000 reached Platinum Honors and its 75% bonus, which produced 3.5% here. That bonus now sits at the Premier tier and requires $1M. Same balances, lower tier, half a point less back. Our full breakdown of the change covers every affected card.
The Investment Hack: You don’t need $100k in cash sitting in a low-interest savings account to qualify. We keep our balance invested in low-cost Vanguard ETFs within our Merrill Edge account. This allows our money to grow with the market while simultaneously unlocking the highest credit card reward tiers.
The Stack: 5% Total Rewards
When we swipe our BofA card at the Costco register:
- 2% accumulates in our annual Costco reward check.
- 3% hits our Bank of America cash rewards balance.
- Total: 5% cash back on every diaper box and rotisserie chicken.
At the Premier tier ($1M+ in balances) the second layer is 3.5% and the stack reaches 5.5%, which is what this post described before the 2026 program change.
Layer 3: The "Two-Player" Mode (Beating the Cap)
There is one "gotcha" with the Bank of America Customized Cash Rewards card: it has a spending cap. You only earn 2% (boosted to 3%) on the first $2,500 in combined choice category/grocery/wholesale club purchases each quarter.
With a toddler and a high run-rate at Costco, we sometimes blow past $2,500 every three months, on top of the online shopping spend that earns 4.5% on the same card.
The Solution: My spouse and I each have our own Bank of America Customized Cash Rewards card.
- Player 1 Limit: $2,500/quarter
- Player 2 Limit: $2,500/quarter
- Total Capacity: $5,000/quarter ($20,000/year)
By holding two separate cards, we effectively double our reward-eligible spending bandwidth. We simply label one card "Costco Card A" and the other "Costco Card B" and swap them out once we see the first one hit the limit on our banking app.
The Bottom Line
Let's run the numbers for an annual Costco spend of $10,000 (about $830/month). While that is a high number, it is a realistic target for a family that relies on Costco for everything from weekly groceries and diapers to electronics and travel.
Here is how the math shakes out when comparing a standard credit card to this stacked strategy:
- Standard 1.5% Card: $150 cash back
- Our 5% Stack: $500 cash back ($200 from Costco + $300 from BofA)
- CardSavvy Take: This is exactly the kind of "hidden multiplier" our algorithms look for.
That is an extra $350 a year in our pocket. When you are spending that much volume, leaving 3.5 points on the table isn't a rounding error.
Disclaimer: This post is for informational purposes only. Bank of America and Costco terms are subject to change. Check current fee structures and reward limits before applying.
Related on Learn
Hand-picked based on topic and reader interest
How My Family Earns 4.5% Cash Back on Online Shopping (And Doubles Our Rewards Cap)
We stack a Bank of America relationship tier with a strategic category selection to earn 4.5% on almost everything we buy online. Here is the exact setup, and what the 2026 program change cost us.
How to Optimize Your Credit Card Rewards: A Real $34,800 Walkthrough
How much does optimizing your credit cards actually earn? We ran an average US household's $34,800 of spending through CardSavvy Optimize. Three cards, $1,384/yr net, and every number reproducible in the tool.
Are You *Really* Getting 2% Cash Back with Costco Executive? (The Math Says No)
The Costco Executive membership promises a 2% reward, but the $65 upgrade fee eats into your returns. We did the math to find your *true* effective cash-back rate.
Costco PayPal Debit Card Strategy: How to Get 7% Cash Back (2026)
Costco does not accept PayPal directly, but the PayPal Debit Card earns 5% back and stacks with Executive membership for 7% total. Here's the complete strategy.
Get smarter with your cards
Math-first card strategy posts, sent when we publish — not on a schedule. No spam. Unsubscribe anytime.
We respect your inbox.
Ready to optimize your wallet?
Get personalized card recommendations and spending strategies in under 2 minutes.
Free to use. No signup required.
Get My Strategy →Just need an answer for one purchase? Best Card →