Should You Pay Taxes With a Credit Card? Usually Not — Unless You Have a Very Specific Reason
Every spring, the same question comes up: should you put your tax bill on a credit card to earn rewards? The short answer is that federal tax payments can sometimes produce a small positive return, but property tax payments almost never do. The fees are too high.
This is not a "hack." It is a math problem. And for most people, the math says no.
See which cards maximize your everyday rewards →
The Math: Fees vs Rewards on a $10,000 Tax Bill
The IRS allows credit card payments through approved processors, which currently charge about 1.75% to 1.85% for consumer credit cards. Local property tax portals set their own fees, and they are almost always higher.
Here is what the numbers look like on a $10,000 payment:
| Payment Type | Fee | 1.5% Card | 2% Card | 3% Card |
|---|---|---|---|---|
| Federal tax (1.75% fee) | $175 | -$25 | +$25 | +$125 |
| Federal tax (1.85% fee) | $185 | -$35 | +$15 | +$115 |
| Property tax (2.35% fee) | $235 | -$85 | -$35 | +$65 |
| Property tax (2.55% fee) | $255 | -$105 | -$55 | +$45 |
A 2% card barely breaks even on federal taxes and loses money on property taxes. A card earning 3% on tax payments would produce a meaningful spread, but the best-known 3% flat card does not qualify. The Robinhood Gold Card's rewards rules exclude "government services" and "payments made using a third-party service... (including but not limited to rent/housing payments and taxes)," and IRS card payments run through third-party processors. Treat a Robinhood tax payment as earning nothing, which makes the 1.75% fee a $175 loss on $10,000.
(An earlier version of this post ranked Robinhood Gold first for tax payments. That was wrong under Robinhood's current rules, and we have corrected it.)
For a deeper comparison of flat-rate cash back cards, see our Best Unlimited Cash Back Cards guide.
When Paying Taxes by Card Makes Sense
There are four situations where the math can work in your favor.
1. You are meeting a signup bonus spending requirement. If you need to spend $4,000 in three months to earn a $750 welcome bonus, putting a $4,000 tax payment on the card is straightforward. The 1.75% fee ($70) is noise compared to a $750 bonus. This is the strongest use case by far.
2. You have a high flat-rate card and are paying federal taxes. The best cards for this purpose are flat-rate cash back cards that earn above the processor fee:
| Card | Cash Back Rate | Net on $10k (1.75% fee) |
|---|---|---|
| Bank of America Unlimited Cash Rewards | 2.25% (Preferred Honors) to 2.625% (Premier) | +$50 to +$87 |
 Fidelity Rewards Visa |
2% | +$25 |
The Bank of America card leads if you hold large balances there, but it now needs the Premier tier ($1M+ in BofA/Merrill balances) to hit 2.625%; $100k reaches Preferred Honors and 2.25%, which nets $50. The Fidelity card earns 2% with no strings, but the margin is slim. Whatever card you use, check its rewards terms for a tax or government-payment exclusion before you pay; the Robinhood Gold Card is the clearest example of a flat-rate card that excludes them. See our breakdown of the 2026 BofA change if you were counting on the old rate.
3. The processing fee is tax-deductible. The IRS says card processing fees are deductible for business taxes. If you are paying estimated quarterly taxes for a business, the after-tax cost of the fee drops, improving the math. Consult your accountant for your specific situation.
4. You need cash flow timing. A credit card gives you 20-30 days of float before the statement is due. This can matter if you need to time a large payment around other cash flows. But this only works if you pay the statement balance in full. Carrying a balance at 20%+ APR will destroy any rewards gain instantly.
When It Does Not Make Sense
These are the cases where the math clearly loses.
Chasing base rewards on property tax. County convenience fees of 2.3% to 2.55% mean a 2% card loses $35 to $55 per $10,000. Even a card earning 3% on taxes would only net $45 to $65, and that is before you factor in your time dealing with the county portal. The "return on hassle" is poor.
Assuming bonus categories will apply. Tax payments code as MCC 9311 (Tax Payments) under Visa's merchant data standards. This means they earn your card's base rate, not dining, travel, office supply, or other bonus multipliers. Do not assume your 5x category card will earn 5x on a tax payment. It almost certainly will not.
Paying through e-file software. This is a major gotcha. If you pay federal taxes directly through an IRS-approved processor, the fee is 1.75% to 1.85%. But if you pay through integrated e-file software, the IRS fee tables show fees of 2.49% to 2.95%. That difference turns a marginally good idea into a clearly bad one. Always pay through the processor directly, not through your tax software.
Carrying a balance. One month of credit card interest at 20-25% APR can wipe out years of marginal rewards gains from tax payments. If there is any chance you will not pay the statement in full, do not put the tax payment on a card.
The Gotchas Worth Knowing
How you pay changes the fee. Direct processor payments (1.75-1.85%) are much cheaper than e-file integrated payments (2.49-2.95%). This one detail can swing the math from positive to negative.
MCC 9311 means base rate only. Visa's merchant data standards explicitly assign MCC 9311 to local, state, and federal tax collection. Your card's bonus categories will not apply.
IRS payment limits exist. The IRS has frequency limits by tax type: Form 1040 current tax due is limited to 2 card payments per year, estimated tax (1040-ES) is limited to 2 per quarter, and installment agreement payments are limited to 2 per month. Employer federal tax deposits cannot be paid by card at all.
Property tax portals add friction. County-specific examples from public sites show common issues: fees are often non-refundable, cancellations may only be allowed same-day, debit cards may have purchase limits that cause failures, and payments can show as completed but later reverse if the bank rejects the charge. This is not the frictionless experience of swiping a card at a store.
Bonus tip: card payment as automatic extension. The IRS says that if you pay part or all of your estimated federal tax by card when e-filing, that payment acts as your extension, so you do not need to separately file Form 4868. This is a convenience angle, not a rewards play, but worth knowing.
The Better Alternative for Most People
For federal taxes, IRS Direct Pay is free. It pulls directly from your bank account, can be scheduled in advance, and has no processing fee. If the math on your card is marginal (which it usually is), Direct Pay is the better choice.
For property taxes, most counties offer eCheck or bank transfer for a small flat fee (often $1 to $3) compared with the percentage-based credit card fee. On a $5,000 property tax bill, that is $2 vs $117 (at 2.35%). The choice is obvious.
Quick Decision Framework
Use this before putting any tax payment on a card.
- Is the fee below your card's flat cash back rate? If yes, consider it. If no, stop.
- Are you meeting a signup bonus? If yes, the bonus likely swamps the fee. Do it.
- Is it property tax with a 2%+ fee? Skip the card. Pay by eCheck.
- Would you carry a balance? Never. One month of interest erases years of marginal rewards.
- Are you paying through e-file software? Check the fee. It may be 2.5-3% instead of 1.75%.
The Bottom Line
Paying taxes by credit card is a targeted tactic, not a default strategy. Federal tax payments can produce a small positive return with the right card, such as Bank of America Unlimited Cash Rewards at a high BofA Rewards tier. The Robinhood Gold Card does not earn rewards on tax payments. Property tax payments usually lose money because local fees exceed most cards' reward rates.
The honest advice: default to free bank payments unless you have a specific reason not to. A signup bonus, a flat-rate card above 2% that actually earns on federal taxes, or a business tax deduction can make the card payment worthwhile. Everything else is marginal at best and money-losing at worst.
This article is for informational purposes only and does not constitute tax advice. Consult a qualified tax professional for guidance on your specific situation.
Cards Mentioned in This Article
Click any card above to see if it's worth adding to your wallet — personalized verdict in 30 seconds.
Related on Learn
Hand-picked based on topic and reader interest
Credit Card Retention Offers: How to Ask, and the Number to Know Before You Call
A retention offer is worth taking only if it beats your downgrade. Work out your walk-away number before you call, then check the rep's offer against it.
Amazon Prime Uber Eats: $40 Off + $0 Delivery Fee (November 2026)
Prime members get $20 off each of two $25+ Uber Eats orders through Nov 18, then a $0 delivery fee via Amazon. What still costs extra, and the card to use.
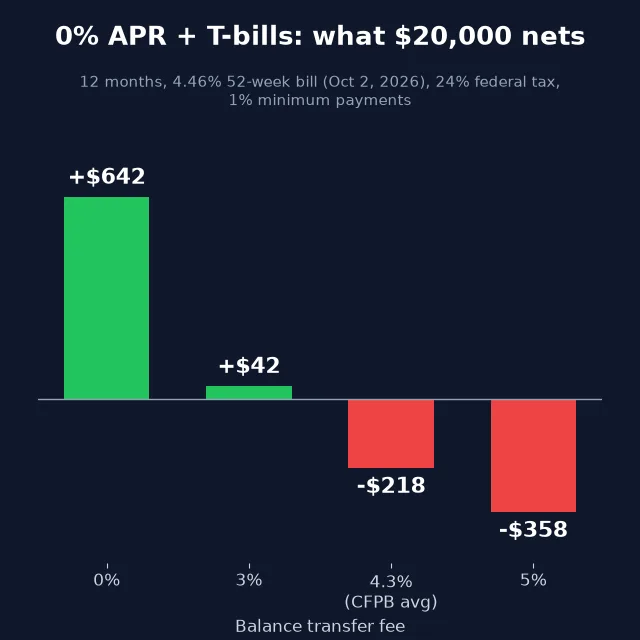
Using a 0% APR Card to Earn Interest: Credit Score and Fine-Print Risks (2026)
Parking a 0% APR balance in T-bills can pay, but the transfer fee, a lost grace period, utilization and mortgage timing decide whether it does. The fine print, checked.

Delta Gold Is a Card to Hold, Not a Card to Spend On
The $150 Delta Gold earns its fee through the checked-bag waiver and TakeOff 15, not through 2x SkyMiles. That distinction decides who should carry it and what belongs on it.
Get smarter with your cards
Math-first card strategy posts, sent when we publish — not on a schedule. No spam. Unsubscribe anytime.
We respect your inbox.
Ready to optimize your wallet?
Get personalized card recommendations and spending strategies in under 2 minutes.
Free to use. No signup required.
Get My Strategy →Just need an answer for one purchase? Best Card →